Economy
Nigeria’s Tough Reforms Pay Off: Economy Recovers, Debt Eases – NRS

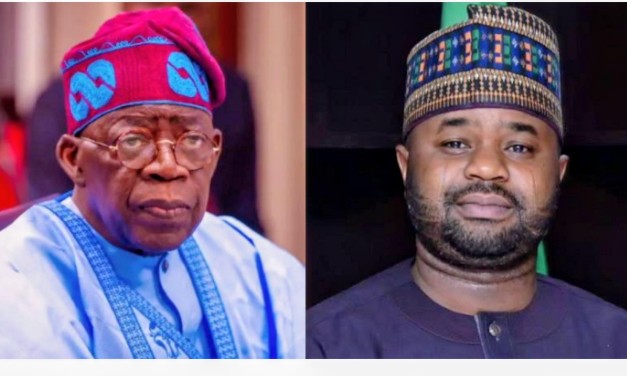
PHOTO: President Tinubu (L) and Executive Chairman Dr. Zacch Adedeji
By Aminat Damilola, Assistant Editor
For the first time, Nigeria’s debt-to-GDP ratio has dropped from 38 percent in 2023 to 32.3 percent in 2026, according to the Nigeria Revenue Service (NRS).
The drop was achieved in more than a decade.
According to the NRS, this development signals a true economic turnaround, rather than a superficial recovery fueled by debt
The agency praised President Tinubu’s Renewed Hope economic reforms for turning things around, calling the difficult steps necessary
In an internal report, the NRS said the Nigerian economy “has moved decisively from acute macroeconomic distress toward a more stable and increasingly resilient footing.”
According to the report, the debt-to-GDP ratio fell from 38 per cent in 2023 to 35.5 per cent in 2025 before dropping further to 32.3 per cent in 2026.
This means that although government debt has grown in naira terms, the economy has grown even faster, resulting in debt accounting for a smaller share of the country’s economic output.
The NRS described this as the first sustained decline in the ratio in more than a decade. The report added that the cost of servicing the debt had also become lighter on government finances, with debt servicing as a share of revenue falling from 68 per cent to a projected 53 per cent, according to the International Monetary Fund.
The NRS traced the country’s economic problems to what it described as four distortions inherited by the Tinubu administration: a fuel subsidy regime the government could no longer afford; a foreign exchange system that scared away investors because it lacked transparency; an oil sector that was not producing as much as it should; and a tax system that was collecting far less revenue than its potential.
External reserves, which serve as the country’s financial cushion for trade and emergencies, have grown more than 12-fold. The report put reserves at $51.9 billion as of July 2026, a 17-year high, compared with $3.99 billion in 2023.
During the same period, the country’s balance of payments position, which measures money flowing into the country against money flowing out, moved from a deficit of $3.34 billion to a surplus of $2.38 billion in the first quarter of 2026.
Nigeria’s stock market has also grown sharply, offering a direct route to wealth for millions of Nigerians who have invested in shares.
The report said the market capitalisation of the Nigerian Exchange rose from N30.36 trillion in 2023 to N161 trillion in 2026. The NRS linked the rally to what it described as improved confidence in government economic management, the recapitalisation of banks and a growing number of Nigerian institutions investing in the stock market.
On taxes, the government said it had more than doubled its revenue. Tax collections rose from N12.3 trillion in 2023 to N27.1 trillion as of July 2026.
The report attributed the increase to the digitisation of tax collection, four new tax reform laws, an overhaul of the revenue service and an executive order that shut down loopholes used to evade taxes.
Oil, which remains central to Nigeria’s economy, has also picked up. Production rose from about 1.2 to 1.3 million barrels per day in 2023 to 1.73 million barrels per day by July 2026, a level equivalent to 104 per cent of the country’s quota under the Organisation of the Petroleum Exporting Countries (OPEC).
The report said Nigeria had also become a net exporter of petroleum products for the first time in decades, helped by a naira-for-crude arrangement between the government, the Dangote Refinery and other local refineries, under which crude oil is exchanged for naira instead of dollars.
The report also noted that exports of petroleum products other than crude oil rose by 51 per cent year-on-year to N6.78 trillion in the first quarter of 2026.
The push to convert vehicles from petrol to compressed natural gas (CNG) has also grown from almost nothing into a programme with significant investment.
Three years ago, Nigeria had no large-scale CNG programme and relied heavily on imported petrol and diesel.
By 2026, more than 100,000 vehicles had been converted to run on gas, with more than $2 billion in investment attracted and over 10,000 jobs created in the process.
The report said CNG could cost 40 to 60 per cent less to run than petrol, while monthly fuel expenditure for some commercial drivers had fallen from about N50,000 to N18,000 after converting their vehicles.
Nigeria’s trade position has also changed direction. The country moved from a marginal trade surplus of about N44.7 billion to a surplus of N7.55 trillion in the first quarter of 2026.
Annual capital importation, which refers to funds brought into the country for investment, rose from $3.9 billion in 2023 to $23.22 billion in 2025.
The report said $10.37 billion came into the country in the first quarter of 2026 alone, with foreign portfolio investment described as particularly strong and foreign direct investment also improving.
On food security, the government declared a state of emergency in July 2023 and followed this with the release of strategic grain reserves, the creation of a N100 billion National Agricultural Development Fund, fertiliser distribution to farmers and an agricultural mechanisation programme.
Federal budget allocation to agriculture rose from N228.4 billion in 2023 to N826.5 billion in the 2025 budget.
Read Also: FG orders NIS to deploy special team to UK for passport issuance
The report said food prices had fallen by about 50 per cent by March 2026, citing figures from the Ministry of Agriculture, although it cautioned that farming requires several planting seasons before increased government support fully translates into higher output.
The report also pointed to gains for workers and families. The national minimum wage doubled between 2023 and 2026.
The number of Nigerian children out of school fell from 20 million to 18.3 million, according to estimates by the United Nations Children’s Fund (UNICEF), a development the NRS linked to government policies and incentives introduced during the period.
Taken together, the NRS said the figures showed an economy that had moved past its most difficult period and was now on firmer ground.
Continue Reading

Maritime5 hours ago
Cabotage Enforcement is My Priority: DG NIMASA

Education7 hours ago
Customs Renovates Ife Girls’ School, Pledges University Scholarships

Business13 hours ago
Tinubu Applauds Coca-Cola’s Planned $1b Investment

Politics14 hours ago
2027: Northern Muslim Women Declare Support for President Tinubu

News1 day ago
Dakuku Peterside: Weak Institutions Stall Nigeria’s Wealth, Prosperity

Maritime1 day ago
Inside Nigeria’s Sea Power: The Rise of NPA as a Maritime Powerhouse

Education2 days ago
Adebayo Williams At 75: A Missing Honour — By Femi Macaulay

Oil & Gas2 days ago
High Hopes as Dangote Launches ₦2.15 Trillion IPO

News2 days ago
2027: LP chieftain sues WAEC, UNN, NYSC over Obi’s credentials

Crime2 days ago
Tension in Osun as Masked Gunmen Kill Adeleke’s Ally ‘Emir’ at Peace Meeting

National2 days ago
Tribute to a Colossus: The Eternal Legacy of Alhaji Bamanga Tukur (1935–2026)

Maritime Safety2 days ago
US Praises Nigeria for Ending 12-Year Maritime Restrictions; Oyetola Credits President Tinubu

News5 months ago
Environmental sanitation resumes in Lagos tomorrow

General News1 week ago
Tribute to a Legal Icon and Master Administrator: Alhaji Yahaya Bukar-Gana

General News5 months ago
Panel recommends 60-month timeline on State Police inauguration

Customs5 months ago
Customs smashes smuggling ring at Tin-Can port, seizes illicit drugs worth ₦18.9b

Customs4 months ago
Customs nets ₦178b at PTML, Miko resumes office

Maritime4 months ago
NIMASA Calls on The Media to Help Drive Blue Economy Growth

Maritime3 months ago
NIMASA Partners Malta to Fast-Track Full Automation of Nigerian Ship Registry

Customs5 months ago
History as Customs CG Adeniyi bags First NIJ alumnus fellowship

Politics3 months ago
“A Blueprint for Prosperity: How Amb. (Engr.) Omar Suleiman Will Transform Adamawa State”

Customs3 months ago
Apapa Customs Intercepts ₦12.7b ‘Canadian Loud’, Expired Drugs in Lagos

Customs3 months ago
Misclassified Levies: Senate Clears Customs of ₦62.2bn Under-Remittance Claim

Customs3 months ago